Debt for what the business needs next.
Refinancing and recapitalizations
For companies replacing expensive or restrictive debt, or returning capital to owners.
The whole capital structure rebuilt around what the business earns: fewer lenders, longer terms, covenants it can live with, and a dividend or buyout where the numbers carry it.
- Financing model
- Lender presentation
- Term sheets compared
- Close
Acquisition financing
For owners and independent sponsors buying a company.
The combined model, what the target really earns once the seller's adjustments are tested, and acquisition debt placed with lenders that fit the deal.
- Combined model
- Seller earnings tested
- Lender match
- Close
Growth capital
For companies funding expansion, equipment or working capital.
Senior, unitranche, asset-based and junior debt, placed from a book of 1,800+ lenders screened by product, credit box, check size, sector and geography.
- Capital plan
- Lender presentation
- Lender match
- Term sheets compared
Selling the company, or buying one?
The same bankers run sell-side and buy-side processes, with the same model and the same package behind them.
A week of preparation.
Built into a day.
BRUNO organizes the documents, reconciles the numbers and builds the financing model, presentation and teaser. A senior banker reviews every page. You approve the package before outreach, and each lender before it sees your name.
That is the time we remove from getting to market. You get a complete credit case, with the gaps identified before a lender has to ask.
Inspect the work that leaves the deskOur estimate for preparing the same materials manually.
Package build time once the required documents are in.
Document collection, your approvals, lender underwriting and closing have their own timelines. One day describes building the package, not receiving an offer or funding.
Inside your file
See your route to market.
What you send. What we build. What happens next. Explore an example of the process you can follow from your own workspace.
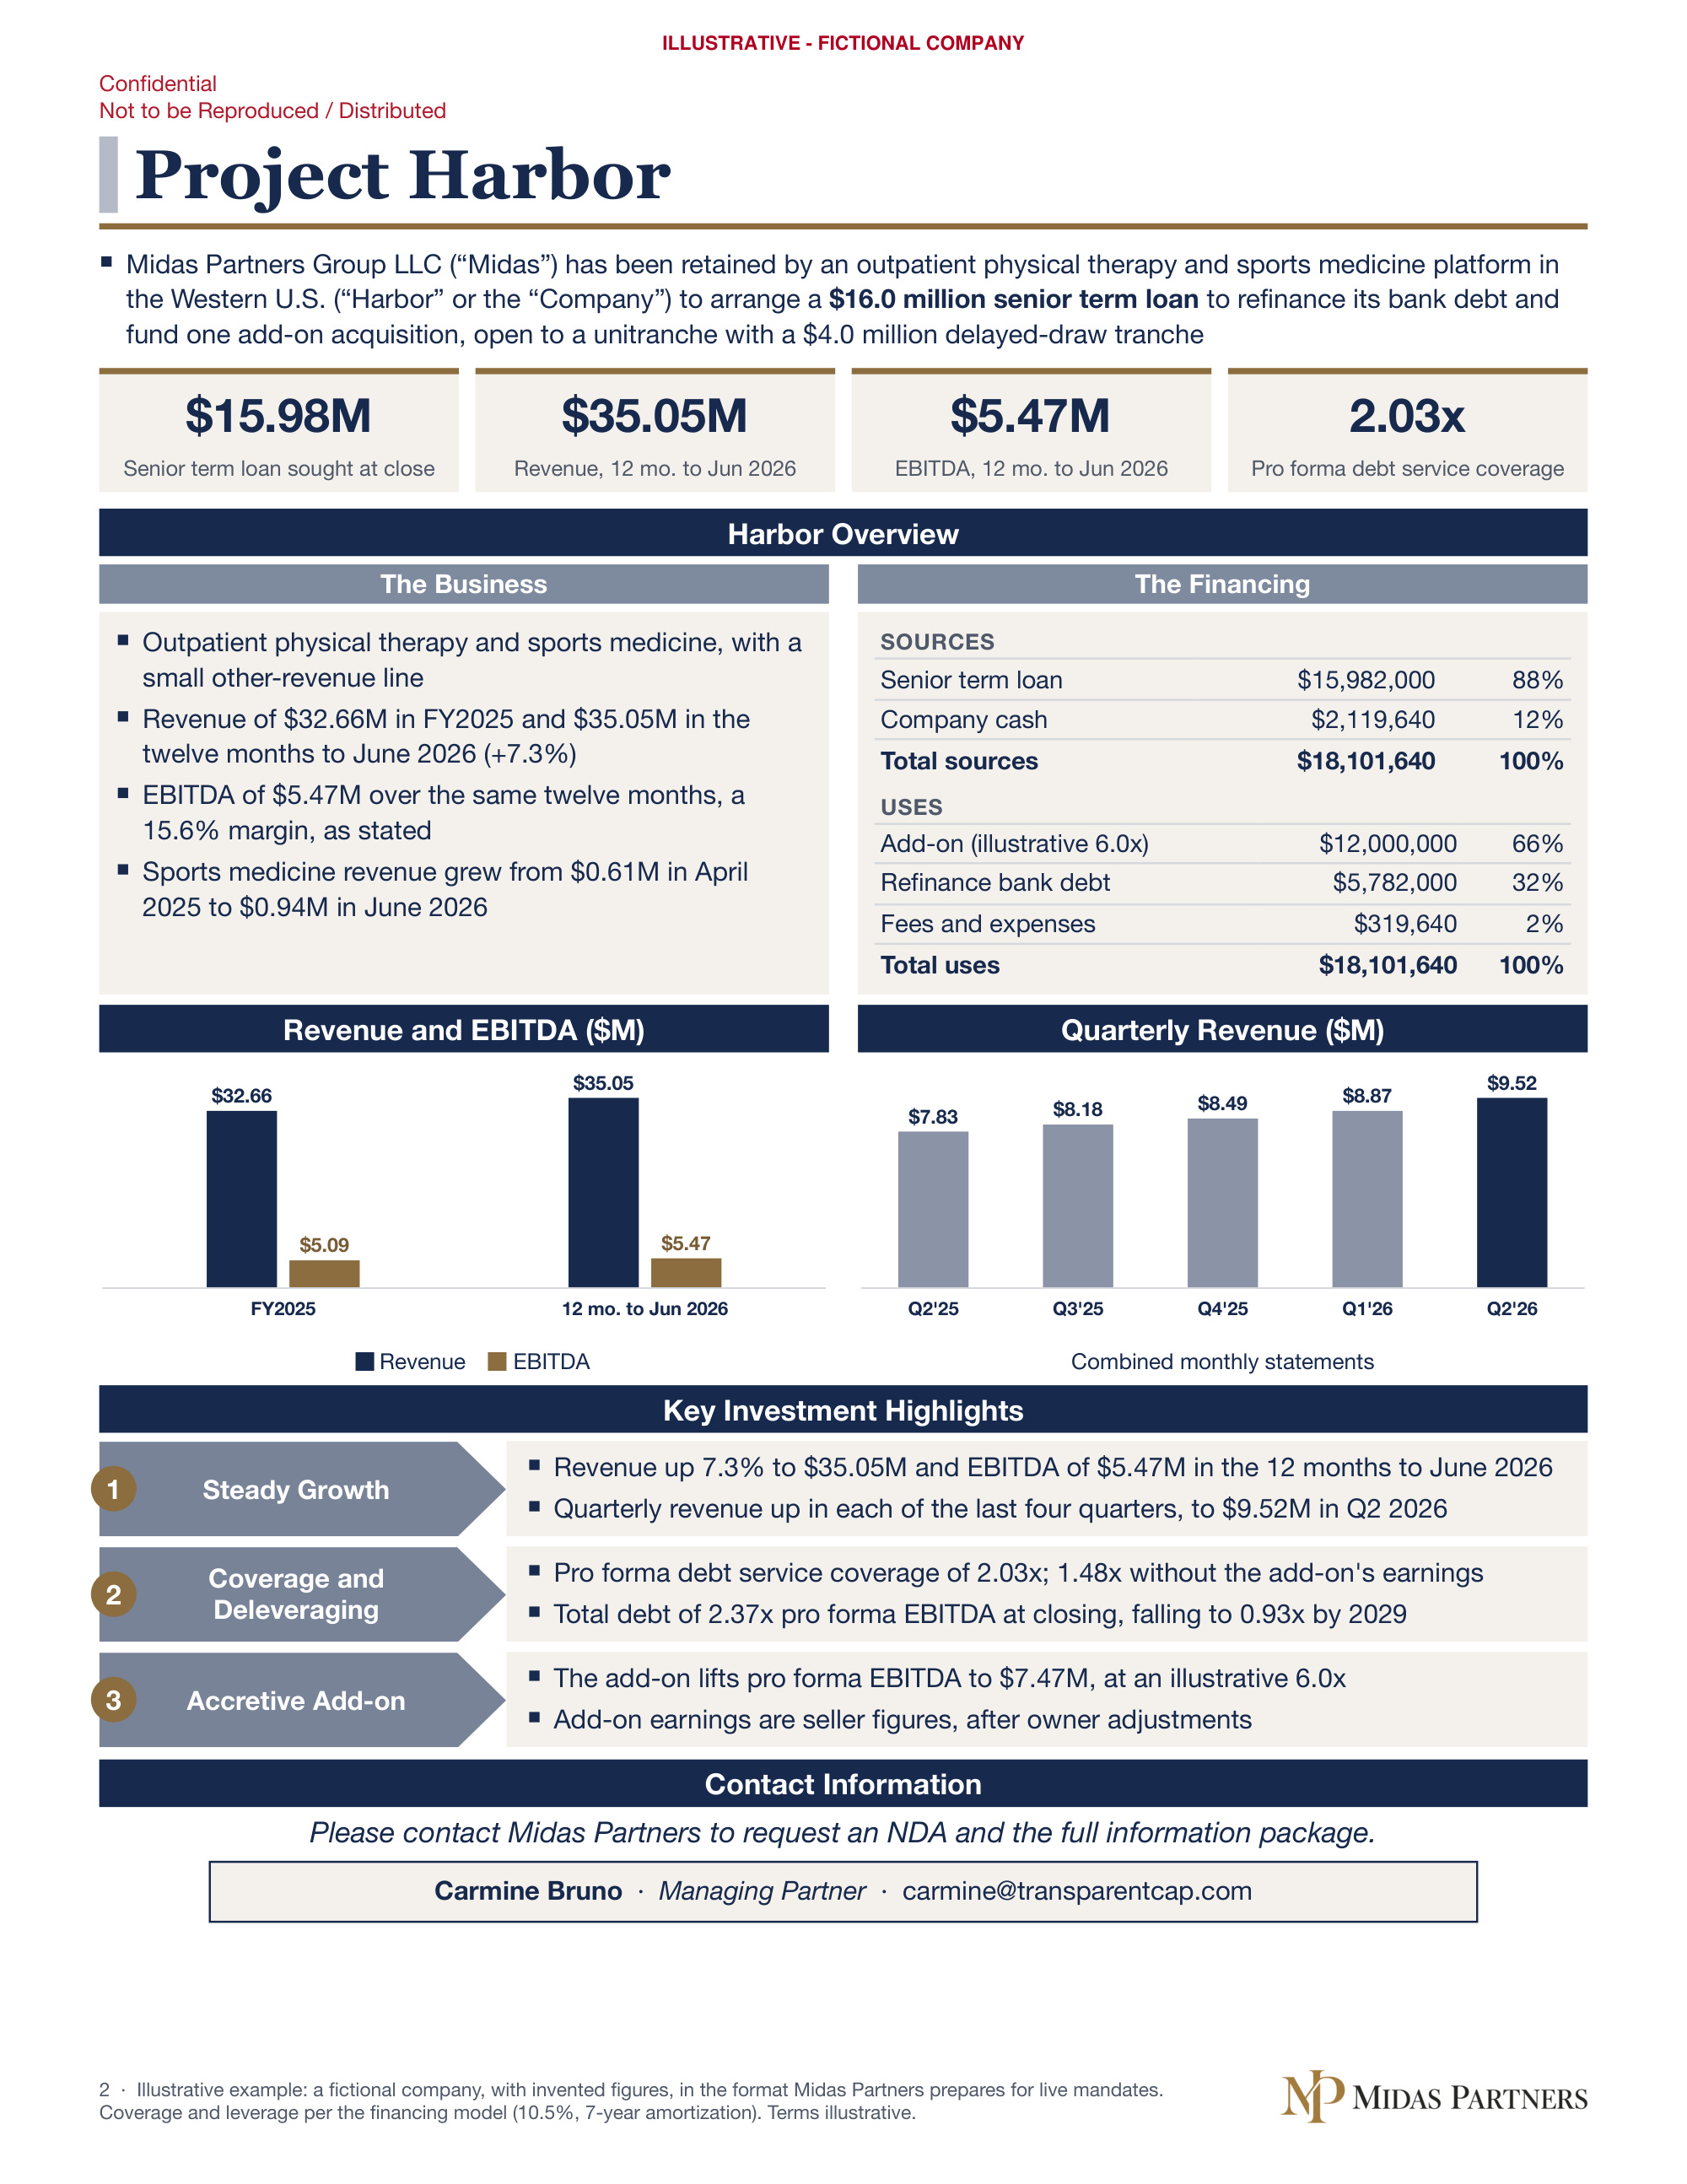
Project Harbor
Illustrative company · example workspace
Example stage 1 of 4: Documents.
Step 1 / 4
Know exactly what is missing.
Send the documents you already have. Your checklist shows what is in, what is still needed, and why it matters.
Your next step
Add the debt schedule. You can start one from the balance sheet already in your file.
Sample document checklist
One item still needed- Business tax returnsIncluded
- Year-to-date P&LIncluded
- Balance sheetIncluded
- Debt scheduleStill needed
Why the debt schedule matters: existing balances and payments affect what the business can borrow next.
Talk through the financing with a senior banker.
A confidential first conversation about the business and what the capital is for. Nothing goes to a lender without your approval.
This is what goes to a lender.
Your financials become a credit case a lender can read. The first page introduces the business, the financing request and the repayment case under a codename.
- The financing request, stated clearly.
- The numbers that support it.
- Your approval before any outreach.
One advisory engagement. Every step covered.
First we make the case. Then you approve it. Only then do lenders see it. The first term sheet starts the comparison; it doesn’t end the search.
- 01
Talk to a banker
A confidential first conversation with a senior banker about the company and what the capital is for. Then you send your banker the financials you already have: business returns, year-to-date statements and a current debt schedule. You do not need to know whether the package is complete.
- 02
Know exactly what is missing
BRUNO, our software, reads the documents, reconciles them and gives you a plain-English list of anything still missing. No email ping-pong. No guessing what a lender means by a full package. Your banker handles anything that requires judgment.
- 03
Approve the package
Once the documents are in, software builds the financing model, the lender presentation and the blind teaser in a day, and a senior banker reviews every page. You correct anything that needs context and approve the final version before it can move.
- 04
Match the right lenders
Software screens 1,800+ lenders by credit box, check size, sector and geography, and your banker narrows them to up to 50 of the strongest fits. You approve the anonymous teaser, and approve by name each lender who asks to see more.
- 05
Go to market under a codename
Matched lenders receive the credit metrics first — not your company, address or owners. Nobody pulls your credit to give an indication. A lender has to say what it would do before it learns whose file it is.
- 06
Keep the answers competing
BRUNO tracks opens, chases questions and keeps the process moving after hours. However many lenders answer, the strongest are run against each other on rate, structure, covenants and timing, and your senior banker negotiates the terms through to close.
The banker. Not the analyst floor.
At a traditional advisor, much of the fee pays for analysts building the model, the lender presentation and the lender list by hand, over weeks. Here software does that work in a day, and a senior banker checks every page.
We don’t carry those analyst hours, so the saving passes through to you.
See the documents we build →No surprises in the lender’s inbox.
- You review the package before outreach.
- You approve by name each lender who asks for your company information.
- Initial outreach uses a codename.
- You decide which term sheet, if any, to accept.
Who works on my deal?
A senior banker runs it from the first call to the close. Software does the analyst work (the model, the lender presentation, the teaser and the lender screen) and the banker checks every page before you see it.
Does one day mean I will have a loan tomorrow?
No. One day is the package build time once the required documents are in. Collecting missing information, your approvals, lender underwriting and closing take additional time. We track those stages separately so you can see what is moving and what needs attention.
Are underwriting and the lender package separate services?
They are part of the same debt advisory engagement. We prepare the credit case, identify the financing routes, build the materials, approach matched lenders under a codename and manage the comparison and execution. The structure depends on your business and what the capital is for.
Do you only raise debt?
Debt advisory is most of what we do: refinancings, recapitalizations, acquisition financing and growth capital. The same bankers run sell-side and buy-side M&A processes, with the same model and package behind them.
Do I need a complete file to start?
No. Start with a conversation: tell a banker the amount and what the capital is for, and send the financials you have. We identify what is missing before we build the lender package.
Will my company be sent to every lender?
No. We send an anonymous teaser only to lenders whose box fits. When a lender asks for the full file, you see its name and decide whether it gets your company information. You decide whether to proceed with any term sheet.
Start with a conversation.
You don’t need a finished presentation. Tell a banker what the capital is for, send the financials you have, and we’ll identify what is missing before anything is built.
Start with what you have
- Two to three years of financial statements
- Year-to-date financials
- Current debt schedule
- What the capital is for